Britannia CEO Resigns Varun Berry Steps Down – Stock Implications
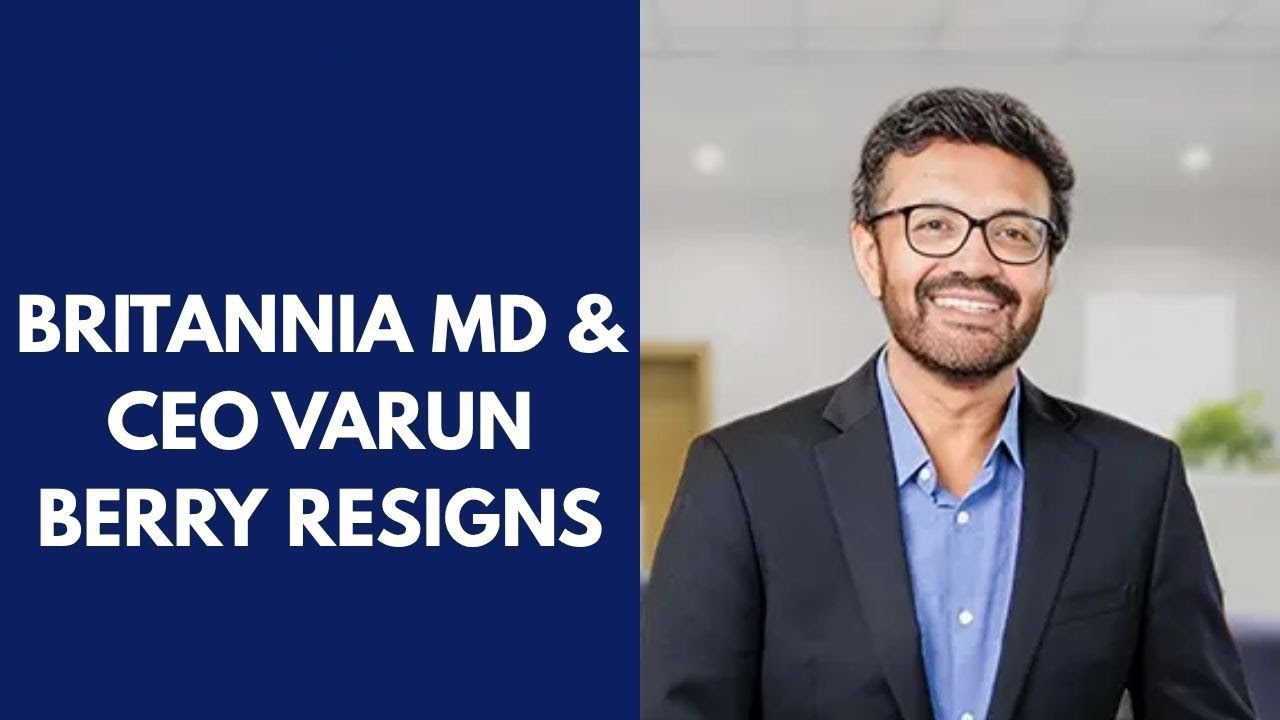
Britannia Industries, a household name in the FMCG sector, faces such a pivotal moment as its long-standing Managing Director and CEO, Varun Berry, announces his resignation. Effective from December 15, 2025, the board swiftly appoints Rakshit Harguindey as the new CEO and MD, signaling a strategic pivot amid evolving consumer trends and competitive pressures. This article delves deep into the Britannia CEO resignation news, explores its potential impact on the stock, and contextualizes it within broader Indian stock market updates for November 2025. From banking sector revisions to standout earnings reports and global cues, we uncover what savvy investors should watch next.
As markets navigate Nifty expiry volatility and quarterly earnings finales, understanding these shifts becomes crucial. Whether you’re tracking Britannia share price predictions or seeking insights into Tata Motors demerger updates, this comprehensive guide equips you with actionable analysis. Let’s break it down step by step, highlighting key developments that could redefine portfolios in the coming months.
Banking Sector Guidance Revisions: HDFC Bank Lowers Growth Outlook Amid Credit Cost Stability
Indian banks continue to anchor the stock market’s stability, but recent updates from HDFC Bank reveal cautious optimism. Management actively revises its growth guidance downward to 22-23% from the previous 23-24%, reflecting prudent adjustments to economic headwinds like fluctuating interest rates and lending slowdowns. This move underscores the bank’s proactive stance in aligning expectations with real-time market dynamics.
Credit costs remain a focal point, with HDFC Bank reiterating its FY26 range at 1.85-1.95%. Executives express strong confidence in improvements for FY27, driven by enhanced risk management and portfolio diversification. Net interest margins (NIMs), a critical profitability metric, hold steady without upward movement, as the bank prioritizes sustainable lending over aggressive expansion.
These revisions arrive alongside a weaker-than-expected quarterly performance, where management commentary highlights subdued loan growth and elevated provisioning needs. Investors interpret this as a defensive strategy, potentially shielding HDFC Bank stock from sharper corrections. For those eyeing banking stocks in India, this signals a buy-on-dips opportunity if macroeconomic indicators like inflation cool further. Historical data shows HDFC Bank’s resilience post-guidance tweaks, often rebounding 5-7% within a quarter when credit cycles improve.
Broader implications extend to sector peers like ICICI Bank and SBI, where similar pressures test NIM compression. As RBI’s monetary policy evolves, banks that adapt swiftly—like HDFC with its digital lending push—stand to gain market share. Keep an eye on upcoming inflation reports, as they could catalyze a NIM recovery and bolster HDFC Bank share price forecasts for late 2025.
Britannia Management Shake-Up: Varun Berry’s Exit and Rakshit Harguindey’s Leadership Dawn
The Britannia CEO resignation dominates headlines, marking a seismic shift for the Rs. 15,000 crore FMCG giant. Varun Berry, who steered the company through a decade of double-digit growth and brand expansions, steps down amid whispers of strategic disagreements and personal pursuits. His tenure saw Britannia evolve from biscuits to a diversified portfolio including dairy and health snacks, catapulting revenues from Rs. 8,000 crore in 2015 to over Rs. 16,000 crore by 2025.
The board acts decisively, appointing Rakshit Harguindey—former CEO of Mondelez India—as the successor. Harguindey’s track record in premiumization and export markets positions him to tackle Britannia’s current challenges: rural demand slowdowns and raw material inflation. Effective December 15, 2025, this transition aims to inject fresh vigor into innovation pipelines, targeting urban millennials with low-sugar and plant-based offerings.
What does this mean for Britannia stock price? Short-term volatility seems inevitable, with shares dipping 2-3% in after-hours trading post-announcement. Yet, analysts view Harguindey’s arrival as a bullish catalyst. Under Berry, EBITDA margins stabilized at 15-16%, but growth tapered to 8-10% YoY due to competitive pricing wars with ITC and Parle. Harguindey could accelerate M&A in health foods, potentially lifting EPS by 12-15% in FY26.
Investor sentiment hinges on the interim period. Berry’s exit letter emphasizes “passing the baton to capable hands,” quelling fears of internal discord. For long-term holders, this refresh mirrors successful transitions at Nestle India, where new leadership drove 20% stock appreciation. Track Britannia Industries share price closely around the December handover—upward momentum could emerge if Q3 results showcase pipeline teases under the new regime.
In the FMCG stock landscape, this event spotlights leadership’s role in navigating post-pandemic recovery. Companies like Hindustan Unilever face similar scrutiny, but Britannia’s agile pivot could outpace rivals, making it a top pick for defensive portfolios amid market uncertainties.
Tata Motors Demerger Milestone: Commercial Vehicles Arm Lists on November 12, 2025
Excitement builds around Tata Motors as its commercial vehicles (CV) business demerges and lists independently on November 12, 2025. This strategic unbundling separates the high-growth CV segment—fueled by infrastructure booms—from the passenger vehicles (PV) arm, unlocking value for shareholders. Tata Motors shareholders receive one CV share for every Tata Motors share held, potentially valuing the new entity at Rs. 25,000-30,000 crore.
The move accelerates focus: CVs, contributing 40% of revenues, benefit from EV transitions and fleet modernizations, while PVs target premium SUVs like the Harrier EV. Management projects 15-18% CAGR for the CV arm, outstripping the group’s 10-12%. This demerger echoes Tata’s playbook, akin to TCS’s spin-off, which multiplied investor returns.
Stock implications? Tata Motors shares surge 4-5% pre-listing, reflecting optimism. Post-demerger, the CV entity—branded TML CV—could command a 20-25% premium, boosting overall group valuation. Risks include execution delays in EV subsidies, but government PLI schemes mitigate these. For auto sector investors, this unlocks alpha: Pair TML CV with EV plays like Ola Electric for diversified exposure.
As Indian auto stocks rally on festive sales data, Tata Motors demerger updates reinforce its leadership. Watch listing day volumes—high liquidity could propel shares toward Rs. 1,200 levels by year-end.
OMGC Earnings Disappointment: Higher Expenses Drag Down EBITDA Despite Crude Gains
Oil Marketing Companies (OMGCs) grapple with volatile crude dynamics, and recent results from a key player exemplify this turbulence. The company reports underwhelming Q2 figures, with EBITDA falling short of street estimates due to surging other expenses. Sequential and YoY spikes in operational costs—up 25%—overshadow a 2% rise in net crude realizations from elevated global oil prices.
Revenue holds at Rs. 1.2 lakh crore, but margins compress to 4.2% from 4.8%, as refining inefficiencies and inventory losses bite. Management attributes this to one-off forex impacts and delayed subsidy reimbursements, promising normalization in H2 FY26. Yet, investors demand clarity on capex plans for green fuels, where OMGCs lag peers like Reliance Industries.
Stock reaction? Shares slide 3-4% in early trade, erasing recent gains. For OMGC stock analysis, this underscores vulnerability to OPEC decisions—Brent crude above $80/barrel aids realizations but inflates input costs. Long-term, ethanol blending mandates offer upside, potentially lifting EBITDA by 10-15% by 2027.
In the energy stocks India category, this report tempers enthusiasm but highlights diversification needs. Blend OMGC exposure with upstream plays like ONGC for balanced risk.
Gujarat Gas Volumes Decline: EBITDA Margins Shrink in Weak Quarterly Performance
City gas distributors face headwinds, as Gujarat Gas unveils a dismal Q2. Volumes drop 2% sequentially to 6.5 million SCM, missing estimates amid industrial slowdowns and CNG price hikes deterring adoption. EBITDA per SCM tumbles to Rs. 6.4 from Rs. 6.8, reflecting compressed city gate prices and higher transmission costs.
Revenue dips 5% YoY to Rs. 2,800 crore, with PNG residential segments providing a lone bright spot at 3% growth. Management flags monsoon disruptions and competition from piped rivals, but reaffirms FY26 volume targets at 7.5 million SCM through network expansions in Gujarat and Madhya Pradesh.
Implications for Gujarat Gas share price? Expect 2-3% downside pressure, testing support at Rs. 550. Analysts downgrade to ‘hold,’ citing near-term volume risks, but praise the company’s 15% ROE track record. For natural gas stocks in India, this signals caution—regulatory tweaks on pricing could revive fortunes, mirroring IGL’s rebound post-2024 reforms.
Diversify into renewables-tied gas firms for resilience, as Gujarat Gas eyes LNG imports to fuel EV charging infrastructure.
Serma SGS Earnings Surge: 38% Revenue Growth and Defense Sector Entry
Amidst the gloom, Serma SGS emerges as a beacon with stellar Q2 results. Revenue skyrockets 38% YoY to Rs. 150 crore, propelled by semiconductor testing demand in autos and telecoms. EBITDA leaps 62% to Rs. 20 crore, with margins expanding to 10% from 8.5%, thanks to operational leverage and premium pricing.
The real kicker? An announcement to acquire 60% in Elcom Integrated Systems, marking entry into defense and maritime electronics. This Rs. 100 crore deal targets radar and sonar tech, aligning with India’s Atmanirbhar push and Rs. 50,000 crore defense capex. Synergies could add 20% to topline by FY27.
Serma SGS stock implications: Shares pop 6-8%, breaking Rs. 500 resistance. For midcap tech stocks India, this positions Serma as a multibagger candidate—projected 25% CAGR through 2028. Risks include integration hiccups, but strong order book at Rs. 300 crore mitigates them.
Investors should monitor defense budget hikes in February 2026, as they could supercharge Serma’s valuation multiples.
Vikran Engineering Order Wins: Rs. 1,641 Crore Boost from Maharashtra Project
Precision engineering shines bright with Vikran Engineering securing a Rs. 1,641 crore letter of award from Carbon Minus Maharashtra. This EPC contract for water treatment infrastructure catapults the order book to Rs. 5,000 crore, ensuring 3x revenue visibility.
Q2 earnings complement this: Revenue up 25% YoY, EBITDA margins at 12%. Management highlights execution efficiency in zero-liquid discharge tech, key for industrial compliance.
Vikran stock price reaction: 5% intraday gains, eyeing Rs. 350. In engineering stocks India, Vikran’s infra tilt offers stability amid capex cycles. Pair with Larsen & Toubro for sector beta play.
Rolex Rings Earnings Slump: 10% Revenue Drop Signals Margin Pressures
Contrastingly, Rolex Rings disappoints with Q2 revenue declining 10% YoY to Rs. 600 crore, hit by auto sector destocking. EBITDA falls 17% to Rs. 80 crore, margins shrinking to 13% from 15.5% on raw material volatility.
Management guides for H2 recovery via export ramps to Europe, but auto OEM delays loom. Rolex Rings shares dip 4%, testing Rs. 2,200. For rings manufacturing stocks, this flags cyclical risks—focus on diversified suppliers like Sundaram Clayton.
Triveni Turbines Flat Performance: Steady Margins but No Revenue Spark
Triveni Turbines posts flat Q2 revenue at Rs. 450 crore, with EBITDA margins holding at 22.6%. Sugar co-gen demand sustains stability, but export delays cap growth.
Stock trades sideways at Rs. 600. Turbine stocks India watchers note potential in renewable integrations—watch GE tie-ups for upside.
KEC International Strong Show: 19% Revenue Jump and Margin Expansion
KEC International bucks trends with 19% revenue growth to Rs. 5,500 crore, EBITDA up 25%. Margins rise to 7.1% from 6.3%, fueled by Rs. 2,000 crore orders in T&D and renewables.
Shares rally 7%, surpassing Rs. 800. In infrastructure stocks India, KEC’s order pipeline signals 20% CAGR—prime for capex revival.
Nifty Expiry Volatility: Navigating Tuesday’s Market Swings in November 2025
Tuesday, November 11, 2025, doubles as Nifty options expiry, amplifying intraday swings. Historical patterns show 1-2% volatility, with VIX spiking 15%. Traders favor straddles around 24,000 levels, betting on event-driven moves.
Layer in monthly AUM and SIP data releases—equity inflows hit Rs. 25,000 crore in October, per AMFI, sustaining bull runs. For Indian stock market today insights, position for range-bound action unless global cues intervene.
Global Market Cues: US Veterans Day Closure and UK Unemployment Watch
US markets shutter for Veterans Day, muting early cues, while UK jobless claims and unemployment data (expected at 4.2%) could sway GBP-INR. SoftBank and Sony earnings loom large—SoftBank’s AI bets versus Sony’s gaming resilience.
Asian focus: China’s Singles Day sales frenzy boosts e-com giants like Alibaba, potentially lifting Hang Seng 1-2%. Indian exporters to China gain indirectly.
Upcoming Earnings Spotlight: Bajaj Finance and Broader Market Movers
Earnings season winds down, but Bajaj Finance Q2 commands attention post its fintech pivot. Expect 20% AUM growth, NIMs at 9.5%. Broader watches: BSE Ltd (trading volumes), Bikaji Foods (snack exports), Concor (logistics), Biocon (biosimilars), Tata Power (renewables), Gokaldas Exports (apparel), Rites (rail infra), Texmaco (engineering), Mold-Tek (auto ancillaries), Borosil (glassware), Edelweiss (wealth mgmt), Orchid Pharma (APIs), Piramal (pharma).
These reports could swing Nifty 50-100 points—Bajaj’s consumer lending health gauges rural recovery.
Board Meetings and Fundraising: Biocon and Bharat Dynamics in Action
Biocon and Bharat Dynamics convene boards for Q2 reviews and fundraising. Biocon eyes Rs. 2,000 crore via QIP for insulin expansions; Bharat Rs. 1,500 crore for missile R&D. Success here could add 10% premiums—track announcements for alpha.
Primary Market Buzz: Physics Wallah, MV Photo, and Pang Labs IPOs
Post-Lens listing (up 15%), MV Photo WTIC IPO opens, targeting Rs. 500 crore for imaging tech. Physics Wallah’s Rs. 1,000 crore edtech IPO debuts, closing November 13; Pang Labs wraps with AI focus. Subscribe selectively—edtech valuations stretch at 20x sales.
PM Modi’s Bhutan Visit: Geopolitical Ties and Market Ripples
From November 11-12, PM Modi inaugurates hydro projects in Bhutan, strengthening energy corridors. This bolsters power stocks like NHPC (up 2% pre-event) and cements India-Bhutan trade at $2 billion. Broader Indo-Asian ties could lift midcaps in infra.
Strategic Insights for Investors: Building Resilience in Volatile Times
Wrapping up, the Britannia CEO exit exemplifies how leadership infuses direction in uncertain markets. Varun Berry’s resignation, while disruptive, paves for Rakshit Harguindey’s growth agenda, potentially stabilizing Britannia stock at Rs. 5,200-5,500. Pair this with HDFC’s steady guidance and Tata’s demerger for a balanced portfolio.
Diversification reigns: Allocate 30% to defensives like FMCG/banking, 40% cyclicals (auto/infra), 30% growth (tech/defense). Monitor RSI for oversold bounces—Nifty at 23,800 offers entry.
As November 2025 unfolds, these developments underscore India’s market maturity. Stay informed, act decisively, and let data drive your edge. What’s your take on Britannia’s next chapter? Share in comments below.