BEL Secures Rs 792 Crore Defence Orders: Boosting India’s Defence Sector
Bharat Electronics Limited (BEL) continues to dominate headlines in India’s burgeoning defence industry. As a Navratna public sector undertaking, BEL recently announced a significant achievement by clinching additional orders valued at Rs 792 crore. This development not only underscores the company’s pivotal role in enhancing India’s military capabilities but also signals robust growth prospects for defence stocks in India during 2025. Investors closely monitor BEL share price movements, especially amid rising geopolitical tensions and the government’s push for self-reliance in defence manufacturing under the Atmanirbhar Bharat initiative.
The latest order wins come at a time when India’s defence sector experiences unprecedented expansion. With exports surging and domestic production ramping up, companies like BEL lead the charge. This article delves into the details of these orders, analyzes BEL’s financial health, explores its stock performance, and examines its future pipeline. Whether you’re an investor eyeing defence stocks in India or a stakeholder in the aerospace and defence manufacturing space, understanding BEL’s trajectory offers valuable insights into one of the nation’s most strategic industries.
Latest BEL Order Wins: Radars, Drones, and Communication Systems Drive Growth
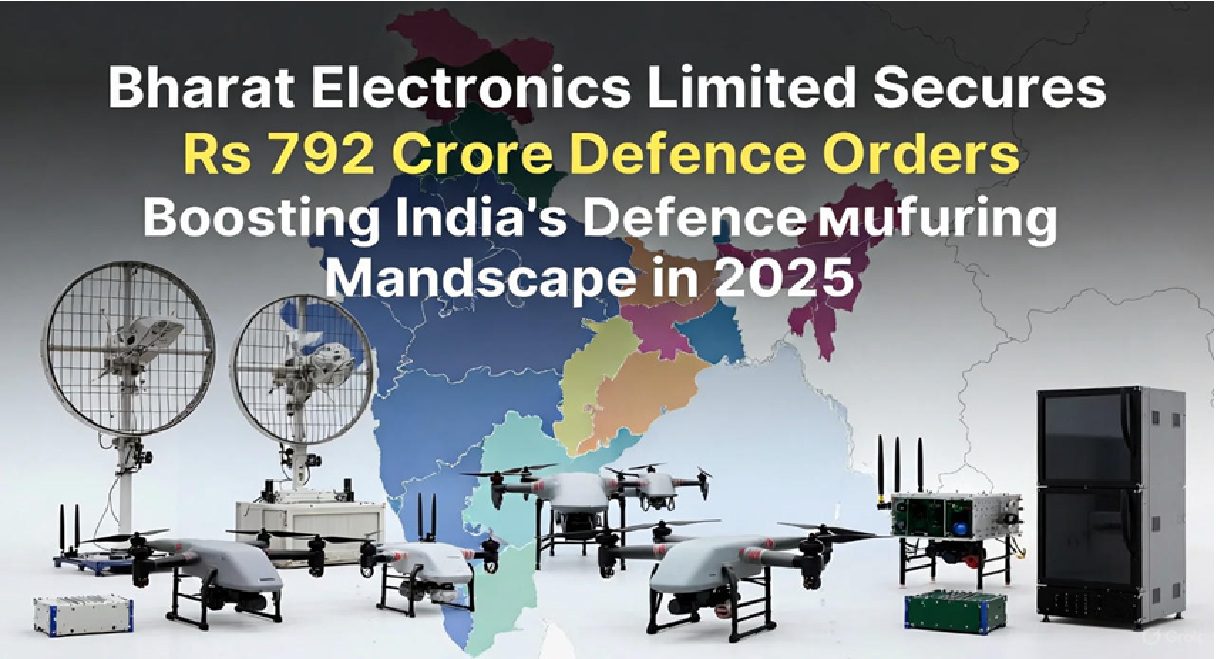
BEL actively secures contracts that fortify India’s defence infrastructure. On November 10, 2025, the company revealed it had bagged additional orders totaling Rs 792 crore since its previous update on October 30, 2025. These contracts span a diverse array of advanced technologies, reflecting BEL’s expertise in defence electronics.
The orders encompass upgrades to defence networks, which ensure seamless connectivity across military operations. BEL also supplies radio communication networks, essential for real-time coordination in the field. Radars form a core component, with BEL’s systems providing critical surveillance and detection capabilities. Communication equipment further enhances interoperability among forces, while drones offer aerial reconnaissance and strike options.
In addition, the deals include combat management systems that integrate sensors, weapons, and command interfaces for efficient battlefield control. Gun sighting systems improve accuracy in artillery and infantry weapons, and the contracts cover upgrades, spares, and services to maintain operational readiness. This mix highlights BEL’s ability to deliver end-to-end solutions, from hardware to ongoing support.
These wins build on BEL’s momentum throughout 2025. By November 4, 2025, the company had accumulated orders worth Rs 14,750 crore for the fiscal year. Management expresses confidence in exceeding the annual target of Rs 27,000 crore in inflows, excluding major projects like the Quick Reaction Surface-to-Air Missile (QRSAM) system. Such achievements position BEL as a cornerstone in India’s defence manufacturing landscape, where innovation meets national security needs.
Experts attribute this success to BEL’s long-standing partnerships with the Ministry of Defence and other armed forces branches. The company’s focus on indigenization aligns with government policies that prioritize local production over imports. As India aims to achieve a defence manufacturing turnover of Rs 1.75 lakh crore by 2025, BEL’s contributions become increasingly vital. These orders not only boost revenue but also enhance technological self-sufficiency, reducing dependence on foreign suppliers.
BEL Stock Performance: Share Price Rally Amid Positive Investor Sentiment
Investors flock to BEL shares as the company demonstrates consistent growth. On November 10, 2025, BEL’s stock opened at Rs 416, slightly above the previous close of Rs 414.25. Throughout the trading session, it reached an intraday high of Rs 420.30, representing a 1.46% gain. This uptick reflects market enthusiasm following the order announcement.
By November 11, 2025, BEL’s market capitalization stood at approximately Rs 3,04,708 crore, underscoring its status as a heavyweight in the defence sector. Analysts from firms like ICICI Securities recommend buying BEL shares, citing strong fundamentals and a promising outlook. Weekly forecasts suggest immediate support at Rs 402.70 and resistance at Rs 428.40, indicating potential for further upside.
The stock’s performance mirrors broader trends in defence stocks in India. Over the past two decades, BEL shares have climbed from around Rs 25 in 2005 to over Rs 416 in 2025, navigating challenges like the 2008 financial crisis and the COVID-19 pandemic. This resilience stems from BEL’s diversified portfolio and government backing.
Positive sentiment arises from BEL’s steady margins and expanding order book. The company maintains an EBITDA margin above 27% for the full year, appealing to value investors. Brokerages like Phillip Capital rate BEL as a “buy,” with price targets ranging from Rs 457 to Rs 550 by 2026. Factors such as increasing defence budgets and export opportunities fuel this optimism.
For retail investors, BEL offers a compelling case in a volatile market. Its inclusion in major indices and consistent dividends make it a stable choice. However, risks like project delays or geopolitical shifts warrant caution. Overall, the recent order wins propel BEL share price higher, attracting both domestic and international attention.
BEL Order Book Update: From Rs 74,453 Crore to Surpassing Annual Targets
BEL’s order book serves as a barometer of its future revenue potential. As of October 1, 2025, it totaled Rs 74,453 crore, climbing to Rs 75,600 crore by November 4, 2025. This growth incorporates the latest Rs 792 crore additions, demonstrating rapid execution and acquisition.
The portfolio includes over 350 main equipment items and more than 1,000 sub-equipment line items, ensuring diversified revenue streams. Key contracts feature the Long Range Surface-to-Air Missile (LRSAM) at Rs 5,000 crore, electronic fuses at Rs 4,500 crore, BMP-2 upgrades at Rs 3,000 crore, and the Akash Army system at Rs 2,700 crore. The top seven orders alone account for about Rs 25,000 crore.
Management emphasizes a balanced product mix across the financial year’s halves, supporting stable margins. BEL anticipates large inflows from upcoming projects, potentially pushing the order book beyond expectations. This robust backlog provides visibility for the next several years, a critical factor for investors in defence stocks.
In comparison to peers like Hindustan Aeronautics Limited (HAL), BEL’s order book highlights its electronics focus. While HAL excels in aircraft, BEL dominates in radars and communication systems. This specialization allows BEL to capture niche markets within India’s defence ecosystem.
The order book’s expansion aligns with national goals. India’s defence exports reached Rs 9,131 crore in the first half of FY26, a 12% year-on-year increase. BEL contributes significantly, exporting systems to friendly nations and bolstering India’s global standing in defence manufacturing.
Financial Performance of BEL: Q2 FY26 Highlights Revenue and Profit Surge
BEL delivers impressive financial results, reinforcing its market position. In Q2 FY26, revenue from operations soared to Rs 5,792 crore, a 25.7% increase from Rs 4,605 crore in the same quarter last year. Quarter-on-quarter, it jumped 30.4% from Rs 4,440 crore.
Operating profit, or EBITDA, rose to Rs 1,702 crore, up 21.6% year-on-year from Rs 1,400 crore. The EBITDA margin stood at 29.38%, slightly down from 30.4% but beating estimates of 26.2%. Profit before tax climbed to Rs 1,728 crore, a 19.6% growth, while net profit advanced to Rs 1,287 crore, 17.7% higher than the previous year’s Rs 1,093 crore.
For the first half of FY26, revenue reached Rs 10,180 crore, up 15.92% from Rs 8,782 crore. Profit after tax grew 20.77% to Rs 2, something crore (approximate based on trends). These figures surpass analyst expectations, with net profit beating estimates by a notable margin.
BEL maintains its FY26 guidance: 15% revenue growth and 27% EBITDA margin. This consistency stems from efficient cost management and a favorable product mix. Earnings per share increased to Rs 3.09 in H1, reflecting shareholder value creation.
Comparing QoQ and YoY metrics reveals BEL’s operational efficiency. Sequential net profit growth of 32.8% highlights accelerating momentum. Factors like timely project execution and supply chain optimizations contribute to these gains.
In the broader context, BEL’s financials outshine many peers in the defence sector. Its low debt and strong cash flows enable investments in R&D, crucial for innovation. As India pushes for defence indigenization, BEL’s profitability positions it to capitalize on emerging opportunities.
Bharat Electronics Limited: History, Evolution, and Role in India’s Defence
Bharat Electronics Limited traces its roots to 1954, when the Indian government established it under the Ministry of Defence to meet the nation’s defence electronics requirements. From humble beginnings in Bangalore, BEL has grown into a multi-billion-dollar enterprise with Navratna status, symbolizing operational and financial autonomy.
Over seven decades, BEL evolves from a basic manufacturer to a leader in advanced technologies. It produces radar systems for air defence, missile guidance electronics, communication networks for the army, navy, and air force, and electronic warfare suites. BEL also ventures into non-defence areas like space, healthcare, and smart cities, diversifying its revenue base.
The company’s manufacturing units span India, employing thousands and fostering skill development. BEL achieves milestones like becoming the first Defence Public Sector Undertaking (DPSU) to reach RE100 status in January 2025, committing to 100% renewable energy and slashing emissions.
BEL plays a central role in India’s defence strategy. It supports programs like Make in India by developing indigenous technologies, reducing import bills. Collaborations with DRDO and international partners enhance its capabilities. At events like Aero India 2025, BEL showcases futuristic tech such as 5G solutions for defence, quantum cryptography, and unmanned warfare systems.
Socially, BEL invests in CSR initiatives, including education and healthcare in rural areas. Its human resources policies emphasize innovation and employee welfare, driving sustained performance.
India’s Defence Sector Growth in 2025: BEL’s Strategic Position
India’s defence industry booms in 2025, driven by increased budgets and export focus. The sector targets Rs 1.75 lakh crore in manufacturing turnover, with exports already hitting Rs 9,131 crore in H1 FY26. Government reforms, including higher FDI limits and simplified licensing, accelerate this growth.
BEL stands at the forefront, benefiting from structural shifts. Under the Technology Perspective and Capability Roadmap (TPCR) 2025, BEL secures long-term orders across forces. Its dominance in electronics complements players like HAL and BDL, creating a synergistic ecosystem.
Geopolitical factors, such as border tensions, spur investments in modernization. India’s push for self-reliance post-Operation Sindoor expands global opportunities, with BEL exporting to over 20 countries.
Challenges include supply chain disruptions and competition from private firms. However, BEL’s established infrastructure and R&D investments mitigate these. Analysts predict the sector’s compound annual growth rate (CAGR) at 12-15% through 2030, with BEL poised for double-digit gains.
Upcoming Projects and Pipeline for BEL: QRSAM, Project Kusha, and Beyond
BEL’s pipeline brims with high-value projects, ensuring sustained growth. The QRSAM system, expected by March 2026, headlines the list. Other initiatives include Shatrughat and Samaghat for border security, next-generation communication systems, additional Light Combat Aircraft (LCA) orders from HAL, Shakti electronic warfare, Ground-Based Mobile Elint System (GBMES), mountain radars, and High Altitude Multi-Mission Electronic Reconnaissance (HAMMER) systems.
Longer-term, Project Kusha for long-range air defence may materialize by December 2029. BEL also eyes Ashwini Radar (Rs 25 billion), Electronic Warfare Suite for MI-17 helicopters (Rs 20 billion), and ATULYA orders (Rs 20 billion).
Emerging technologies like 5G defence solutions, quantum cryptography, and unmanned systems position BEL for future dominance. At Aero India 2025, BEL plans to unveil these innovations, attracting partnerships.
Management targets diversification into space and healthcare, aiming for non-defence revenue at 20-25% by 2030. With a strong pipeline, BEL anticipates order inflows exceeding Rs 27,000 crore annually.
Why Invest in BEL Shares? Analysis for 2025 and Beyond
BEL appeals to investors seeking growth in defence stocks. Its share price target for 2025 ranges from Rs 450 to Rs 550, driven by order wins and financial strength. By 2030, projections reach Rs 900-1,200, factoring in AI integration and exports.
Risks include execution delays and market volatility, but BEL’s low valuation multiples (compared to peers) offer a safety margin. Dividends and buybacks enhance returns.
For portfolio diversification, BEL complements tech and industrial stocks. Analysts from Equitymaster and Groww highlight its potential, rating it a strong buy.
Conclusion: BEL Leads India’s Defence Renaissance
Bharat Electronics Limited exemplifies excellence in India’s defence sector. With Rs 792 crore orders bolstering its book, strong financials, and a promising pipeline, BEL drives national progress. As defence stocks in India gain traction in 2025, BEL remains a top pick for investors. Its commitment to innovation and sustainability ensures a bright future, contributing to a self-reliant India.