Al-Nassr Set Their Sights on Conquering the Saudi Pro League
Title: Cristiano Ronaldo and Al-Nassr Eye Saudi Pro League Glory After Dramatic Weekend Twist
The recent crowning of the league leaders by Al-Hilal provided Al-Nassr and Cristiano Ronaldo a glowing beam of optimism in the title race which is now deemed as fascinating. The recent matches not only lived up to expectations but also matched the unpredictability associated with the sport and history defining moments were created making the race for the title even more interesting.
Al-Hilal Stunned by Al-Khaleej Cameback
Al-Khaleej shocked the league table leaders This was a surprising change given how the season had started off for Al-Hilal and not many would have predicted Al-Khaleej to come from behind Given the early lead mitigrov and leonardo gave Al Hilal a strong hold of the game at half time, the second half turned into a sour tale for Jorge Jesus men.
Just as the break occurred they netted in a quick goal and another followed the two goals which disturbed Al-Hilals rhythm. The last nail in the coffin came through Fabio Martins who scored a phenomenal winner goal in the final minutes which brought The finale at the Prince stadium elevated the people The Stunner of Al-Khaleej has kept Al-Hilal at a distance of 6 goals with Al-Nassr who is now at the second spot.
Al-Nassr’s missed chance
Cristiano Ronaldo and his club Al-Nassr did not take advantage of their decisive match-al Hilal as Al-Nassr was beaten 2-1 in a home match against Al-Qadisiyah Al. The Portuguese750 star was incredible as he managed to put one past the opponent in the first half of the third minute marking a world record being the first athlete to score against another in2759 different matches.
However, Al-Qadisiyah which earned promotion in the Saudi pro league last season was determined. Jules Quinones got the equalizer in the 70th minute and on second half, Pierre-Emerick Aubameyang formerly played for the Spanish side Barcelona, completed the turn around. The result has left Al-Nassr in a very difficult position when it comes to the title race.
Ronaldo’s ground breaking achievement.
Cristiano Ronaldo continues to carve his footprint into history books as he seems to do109 even with advancing age. The goal he scored for Al-Nassr against Al-Qadisiyah not only constituted a new record but also still proves mandrin , the 39 year old man’s timeliness on the201 field. In only 80 appearances for Al-Nassr, Ronaldo has amassed an incredible 69 goals and 18 assists in over just a year span for a single club. He scored 44 goals and assisted 13 in his293 last season continuing his incredible legacy in Saudi football.
This time, Ronaldo continues to be vital for Al-Nassr, with a thirteen-game league goal involvements of 11 goals and 3 assists across 16 matches in all tournaments. He is the highest paid footballer in the world with an annual salary of $220 million and with his name, the Saudi Pro League got unmatched spotlight.
Title Race Tightens
Al-Hilal suffered a setback in that match giving a chance to teams like Al-Nassr and Karim Benzema’s Al-Ittihad to go higher up. For now, Al-Hilal is 6 points ahead of Al-Nassr and also has 1 game in hand so every upcoming match is extremely crucial for both teams. Not having closed the gap leaves any prospective fixtures extremely competitive especially with the likes of Al-Shabab and Al-Qadisiyah right behind them.
On the other hand, Al-Ittihad has a good chance to improve their standing even more. Winning against Al Fateh would hand them Al-Hilal’s place at the top of the table making the league’s midseason clashes ever more crucial.
Focus Shifts to AFC Champions League
For the time being both Al-Hilal and Al-Nassr will shift their focus to the AFC Champion League. Al-Hilal is up against Al Sadd and Al Nassr will face Al Gharafa for their continental fixtures whick will be a good test for the resilience and squad depth of the teams.
After playing in the Champions League, the attention will shift back to the domestic league. Al Hilal will travel to Al Shabab, while Al Nassr will entertain Damac and these matches may be decisive in the title race.
Can Ronaldo Help Al-Nassr Achieve Greatness?
Cristiano Ronaldo has transformed the picture at Al-Nassr ever since he joined them in January this year. However, despite claiming individual accolades and features, the club has been unable to achieve league glory. Last time Al-Nassr won the Saudi Pro League title was in 2019 and in the last two seasons they finished second.
Ronaldo has already been instrumental in winning trophies including the last season’s Arab Club Champions Cup. Without a league title in his haul, the winner of five Ballon d’Ors will be eager to ensure that Al-Nassr achieve more success during his tenure as a captain.
Conclusion
The Saudi Pro League is becoming more engrossing, with the twists and turns forcing the supporters to not leave their sitting positions. The fact that Al-Hilal lost, Al-Nassr’s blowing of a good chance and Cristiano Ronaldo’s new achievements mean that an exciting second half of the season is just around the corner. And as title contenders have domestic followed by continental assignment, the battle for the title will only get juicier.
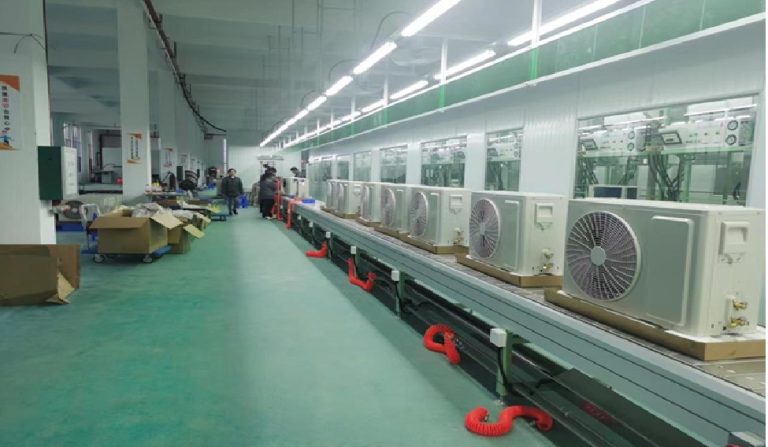
![PG Electroplast Ltd: Comprehensive Fundamental Analysis and Investment Outlook PG Electroplast Ltd (PGEL) represents a compelling case study in India's rapidly expanding Electronic Manufacturing Services (EMS) sector, yet recent quarterly results reveal both the promise and perils of operating in this dynamic industry. The company's Q1 FY26 results demonstrated a mixed performance with revenue growth of 13.9% year-over-year but a concerning 20% decline in net profit, accompanied by significant cuts to full-year guidance that sent shares tumbling over 20% on August 8, 2025. This comprehensive analysis examines PGEL's fundamental strengths and weaknesses, positioning the investment opportunity within the broader context of India's manufacturing transformation and the China+1 supply chain diversification trend.[1][2][3] Financial Performance Analysis: Growth Momentum Meets Margin Pressure Revenue Growth Trajectory and Seasonality Challenges PG Electroplast's revenue performance in Q1 FY26 showcased both the company's underlying growth potential and vulnerability to seasonal and weather-related disruptions. Consolidated revenues reached ₹1,503.85 crores, representing a solid 13.9% year-over-year increase from ₹1,320.68 crores in Q1 FY25. However, this growth came against the backdrop of early monsoon arrivals that significantly impacted the crucial summer air conditioning season, dampening what should have been peak demand period for room air conditioners (RACs).[1] PG Electroplast Revenue Growth Trajectory showing strong historical growth with moderated FY26 outlook The product business, which has emerged as PGEL's primary growth driver, contributed 77.1% of overall revenues and demonstrated resilience with 16.7% year-over-year growth. Within this segment, the company's strategic positioning became evident: RACs grew 15.1% despite weather challenges, washing machines surged 36.1%, while coolers declined marginally by 3.9%. This diversification across appliance categories provides some insulation against single-product dependencies, though the RAC segment's dominance means weather patterns remain a critical factor in quarterly performance.[1] The company's five-year revenue trajectory reveals remarkable transformation, growing from ₹639 crores in FY20 to ₹4,870 crores in FY25 – a compound annual growth rate of approximately 44%. This exponential growth reflects both organic capacity expansion and the broader structural shift toward outsourcing by original equipment manufacturers (OEMs) in India's consumer durables market.[4] Profitability Metrics and Margin Analysis The most concerning aspect of Q1 FY26 results was the deterioration in profitability metrics, which revealed underlying operational challenges despite top-line growth. Net profit declined 19.98% to ₹66.98 crores compared to ₹83.70 crores in the previous year, while operating profit margins compressed to 8.06% from 9.89%. This margin compression occurred despite the company's scale advantages and suggests pricing pressures from OEM customers or inefficiencies in cost management.[5] EBITDA performance provided a mixed picture, with absolute EBITDA growing marginally by 3.6% to ₹139.42 crores, but EBITDA margins declining due to the revenue base expansion. The company's gross margins have historically remained stable around 20%, indicating that the margin pressure is primarily occurring at the operational level through higher employee costs, manufacturing expenses, or administrative overheads.[1] Working capital management emerged as a relative strength, with the cash conversion cycle improving to approximately 68 days in recent periods, supported by payables of 80-100 days that help offset higher inventory and receivables cycles. This working capital efficiency becomes crucial given the seasonal nature of the air conditioning business and the need to build inventory ahead of peak summer demand.[6] Earnings Quality and Cash Flow Analysis PG Electroplast's cash flow profile reveals both the capital-intensive nature of the EMS business and management's focus on growth investment. Operating cash flows turned negative at -₹76.59 crores in FY25, primarily due to working capital investments required to support rapid revenue scaling. This negative operating cash flow, while concerning from a short-term liquidity perspective, reflects the natural consequence of aggressive growth rather than underlying business deterioration.[7] The company's free cash flow remained negative due to substantial capital expenditures of ₹488.2 crores in FY25, invested in new manufacturing facilities and capacity expansion. This capital intensity is characteristic of manufacturing businesses scaling rapidly, and the key metric for investors is whether these investments generate adequate returns over time.[8] Interest coverage remained healthy at 5.1 times, indicating comfortable debt servicing capability despite the company's expansion phase. The strong interest coverage provides financial flexibility and suggests that current debt levels are well within management's capability to service even during periods of operational stress.[9] Valuation Analysis: Premium Pricing Amid Growth Expectations Price-to-Earnings and Peer Comparison PG Electroplast's current valuation reflects the market's high growth expectations for the EMS sector, with the stock trading at a P/E ratio of 72.5 times based on trailing twelve-month earnings. This valuation premium becomes more nuanced when compared to EMS industry peers, where PGEL actually trades at a relative discount to several high-growth competitors.[10] P/E Ratio Comparison of PG Electroplast with EMS Industry Peers The peer comparison reveals that PGEL's 72.5x P/E ratio positions it favorably against premium EMS players like Kaynes Technology (128.7x) and Dixon Technologies (121x), while commanding a premium to Syrma SGS Technology (63.1x). This relative positioning suggests the market views PGEL as a high-quality growth story within the EMS space, though still below the valuations accorded to the sector's most premium names.[10] Compared to the broader Indian electronics industry average P/E of 40.9x, PGEL trades at a significant premium that must be justified by superior growth prospects and execution capability. The company's five-year revenue CAGR of 44% and expanding market share in key segments like air conditioners provide some fundamental support for this valuation premium.[10] Book Value and Asset Efficiency Metrics PGEL's price-to-book ratio of 20.1x appears elevated, reflecting both the asset-light nature of the EMS model and the company's strong return generation capability. The high P/B ratio must be evaluated in context of the company's impressive return on equity of 15% and return on capital employed of 25.2%, which justify premium valuations for efficient capital allocators.[1][11] The company's fixed asset turnover ratio of 5.10x demonstrates efficient utilization of manufacturing assets, a critical metric in capital-intensive industries. This efficiency metric suggests that PGEL's management has successfully scaled operations without proportionate increases in fixed asset investments, contributing to the strong return metrics.[1] Enterprise value-to-EBITDA of 39x and enterprise value-to-revenue of 4.1x further confirm the premium valuation, which appears justified only if the company can sustain high growth rates and improve profitability over time. The recent guidance cuts raise questions about the sustainability of growth expectations embedded in current valuations.[10] Dividend Policy and Shareholder Returns PGEL maintains a conservative dividend policy with a current yield of just 0.03%, reflecting management's focus on reinvesting cash flows into growth opportunities rather than returning capital to shareholders. The company declared a dividend of ₹0.25 per share for FY25, representing a minimal payout ratio that preserves capital for expansion investments.[11] This capital allocation approach aligns with the growth phase characteristics of the EMS industry, where companies must invest heavily in new facilities and capabilities to capture market share. Investors seeking dividend income would likely find more attractive opportunities elsewhere, while growth-oriented investors may appreciate the reinvestment strategy if it generates adequate returns. Growth Potential and Competitive Positioning Industry Tailwinds and Market Opportunity The Indian EMS sector presents compelling structural growth drivers that benefit companies like PG Electroplast positioned at the intersection of multiple favorable trends. India's electronics manufacturing is projected to reach ₹27.7 lakh crores by FY28, representing a robust 27% CAGR from FY23 levels. This growth trajectory is supported by increasing domestic consumption, global supply chain diversification, and government policy support through schemes like Production Linked Incentives (PLI](https://www.tgnns.com/wp-content/uploads/2025/08/PG-Electroplast-Ltd-Comprehensive-Fundamental-Analysis-and-Investment-Outlook-768x447.jpg)